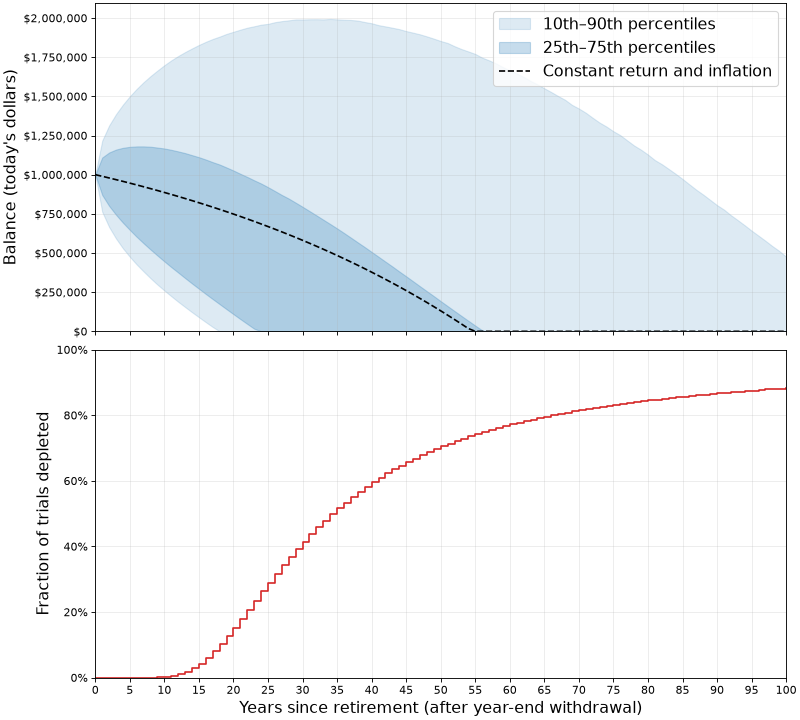
Monte-Carlo Simulations
Monte-Carlo simulations are a statistical method used to model complex systems by running many random trials. The article explains how this technique is applied in finance, physics, and machine learning, highlighting recent advancements and practical examples. It also covers the computational challenges and best practices for implementing efficient simulations. Readers learn how to set up simulations, choose random number generators, and parallelize workloads to reduce.