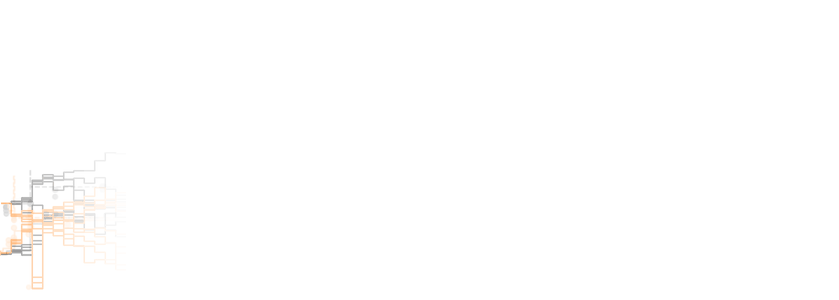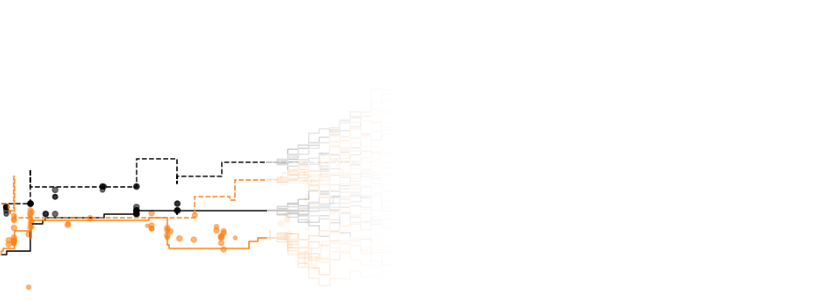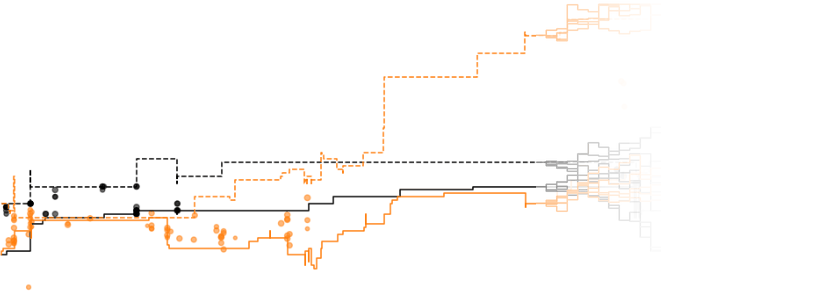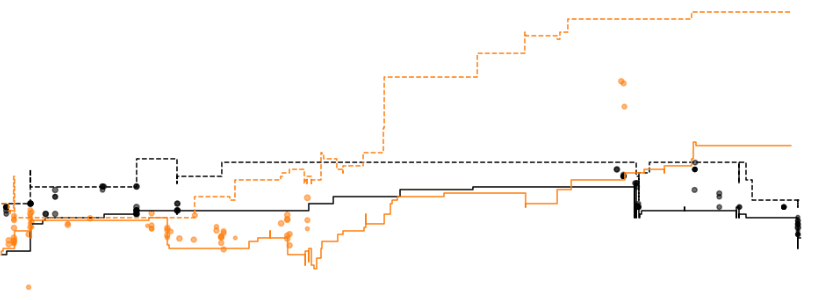
Can you use autoregressive diffusion to generate market data?
A Hacker News discussion poses the question of whether autoregressive diffusion models can be employed to synthesize financial market data. Participants reference recent advances in diffusion‑based generative AI, noting that autoregressive variants may capture temporal dependencies in price series. The thread weighs potential benefits for simulation and testing against challenges in preserving realistic statistical properties and addressing regulatory concerns.